BUSINESS INSURANCE · WORKERS’ COMPENSATION
Workers’ comp begins with the work your team does.
Employees, job duties, payroll and the states where people work all shape a workers’ compensation conversation. We help employers gather the right questions, review available policy options and understand what to confirm as the team grows or changes.
Serving employers in Colorado, Nebraska and Arizona, plus other licensed states where available. State rules, eligibility and actual policy terms vary.
UNDERSTAND THE POLICY
Questions to ask before choosing coverage.
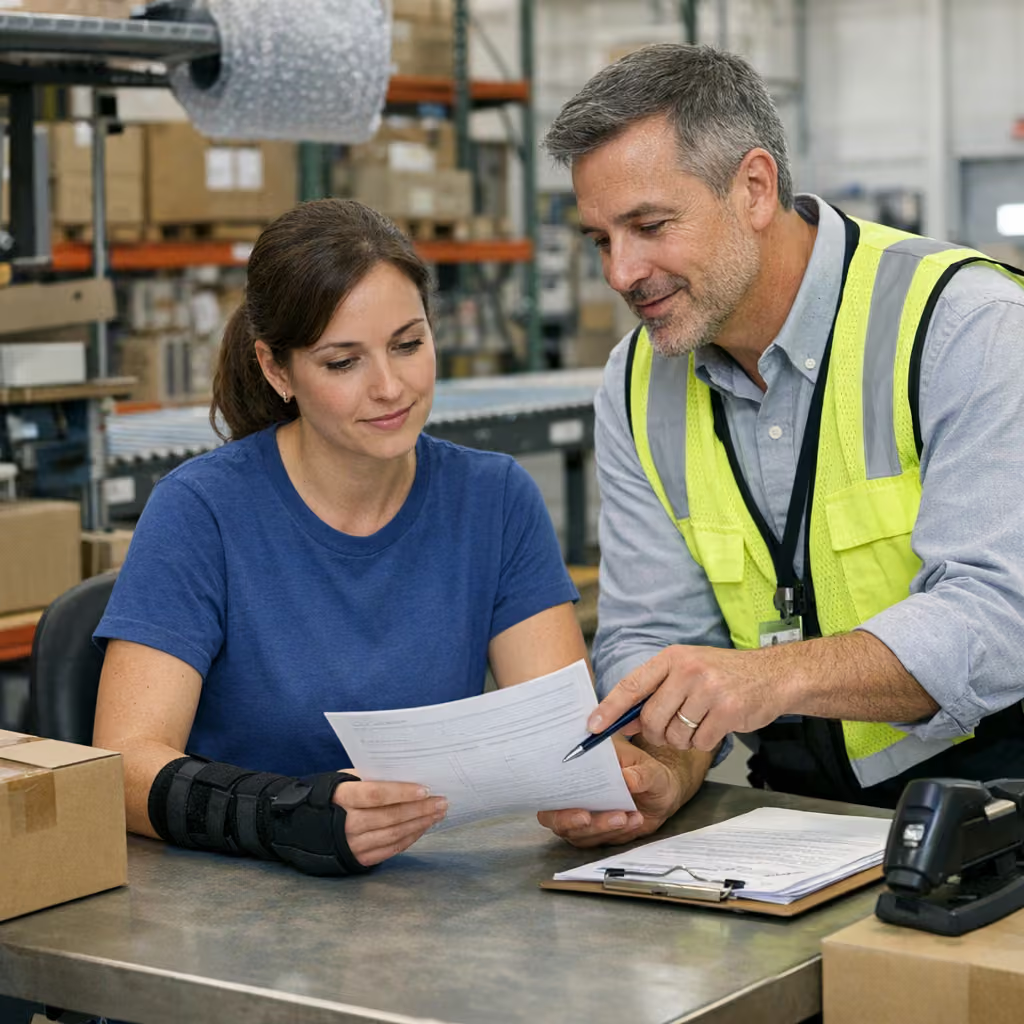
Workers’ compensation is intended to address qualifying work-related injuries or illnesses under applicable state rules. Benefits, employer obligations, exclusions and reporting procedures depend on the jurisdiction and policy—not on a general description here.
Who does the work?
List employees, part-time or seasonal staff, owners and any subcontractors you rely on. Ask a qualified professional how the applicable state treats those roles; a job title or contract label alone should not be your coverage plan.
What work is performed?
A restaurant kitchen, retail store and construction jobsite have different day-to-day tasks. Describe actual duties and locations so the carrier can evaluate classifications and underwriting accurately.
What payroll should be estimated?
Use the best available payroll figures for the policy period and ask how adjustments or a later premium audit work. Keep records when hiring, changing duties or adding locations.
STATE RULES MATTER
Do not rely on another state’s requirements.
Employers may operate across borders or add staff in a new state. Tell your licensed professional where employees live and perform work, and ask which policy and reporting requirements apply. Do not assume a policy issued in one state automatically satisfies every obligation elsewhere.
Workers’ compensation is different from general liability and commercial auto. Those coverages answer other questions; one does not automatically replace another.
Bring these details to the review
- Business type and legal entity
- States and locations where people work
- Job duties and employee counts by role
- Estimated payroll and expected changes
- Existing policy details and renewal date, if available
AFTER YOU ARRANGE COVERAGE
Keep the policy aligned with the team.
New hires, new job duties, added worksites and changed payroll can affect the review. Ask the carrier or licensed agent how to report changes, document payroll and understand any premium audit. Keep a current process for workplace injury reporting rather than waiting for renewal.
We begin with available Farmers options; where appropriate and permitted, our licensed team may explore approved additional markets. A licensed professional confirms state-specific requirements, eligibility, policy language and price. Sending a request does not bind or change coverage.
If someone has already been injured
This website’s consultation form is not a claim-reporting channel. Follow your employer’s and insurer’s injury-reporting procedures and seek appropriate medical attention. Ask your carrier or the relevant state agency about required reporting steps and deadlines.
Colorado
Discuss work performed in Colorado, employee roles and any contractors your business uses. Colorado guide.
Nebraska
Include worksites, seasonal teams and work across state lines where relevant. Call (308) 216-3626 or see the Nebraska guide.
Arizona
Tell us where staff actually works and whether duties or locations have changed. Arizona guide.
COMMON QUESTIONS
Before requesting a review.
The team can start with broad information, then confirm the details needed for any available quote.
Are owners or contractors covered automatically?
Do not assume so. Rules and options depend on the state, business structure and actual working relationship; ask a qualified professional to review them.
Does general liability cover injuries to employees?
General liability generally is not a substitute for workers’ compensation. Review each policy and your applicable state requirements.
Can payroll change after the policy starts?
Yes. Ask how estimates, changes during the term and any premium audit are handled under the offered policy.
Is this a claim report or instant quote?
Neither. This form starts a consultation about coverage. Use your employer’s and carrier’s claim-reporting process for an injury; a licensed team member will follow up about any quote request.
READY TO TALK?
Request a workers’ comp policy review.
Choose Business insurance on the form and include the state where your team works. Our licensed team will follow up to ask about staff, duties and payroll. This is not an instant quote or a way to bind coverage.
Call Colorado at (303) 799-0909, Arizona at (480) 296-7414, or Nebraska at (308) 216-3626. Do not include medical, employee or payroll records in this brief form; it is not for reporting an injury or claim.
Kimberly Smith · Commercial Insurance Specialist
Consumer resource: The NAIC small-business insurance guide explains common workers’ compensation considerations. Coverage obligations, classifications and claim rules depend on applicable state law and actual policy terms; this page is general information, not legal advice.