BUSINESS INSURANCE · COMMERCIAL AUTO
Your work vehicles need a work-specific review.
For owners with a service van, pickup or small fleet, start with who owns each vehicle, who drives it, where it is garaged and how it is used. Does your business rent vehicles or use employee-owned cars? How would liability, physical damage, tools and goods in transit be addressed? We’ll help compare available terms; a licensed professional confirms eligibility.
Tell us where your work vehicles are garaged. Vehicles, drivers, locations, carriers and appropriately licensed team members affect available terms.
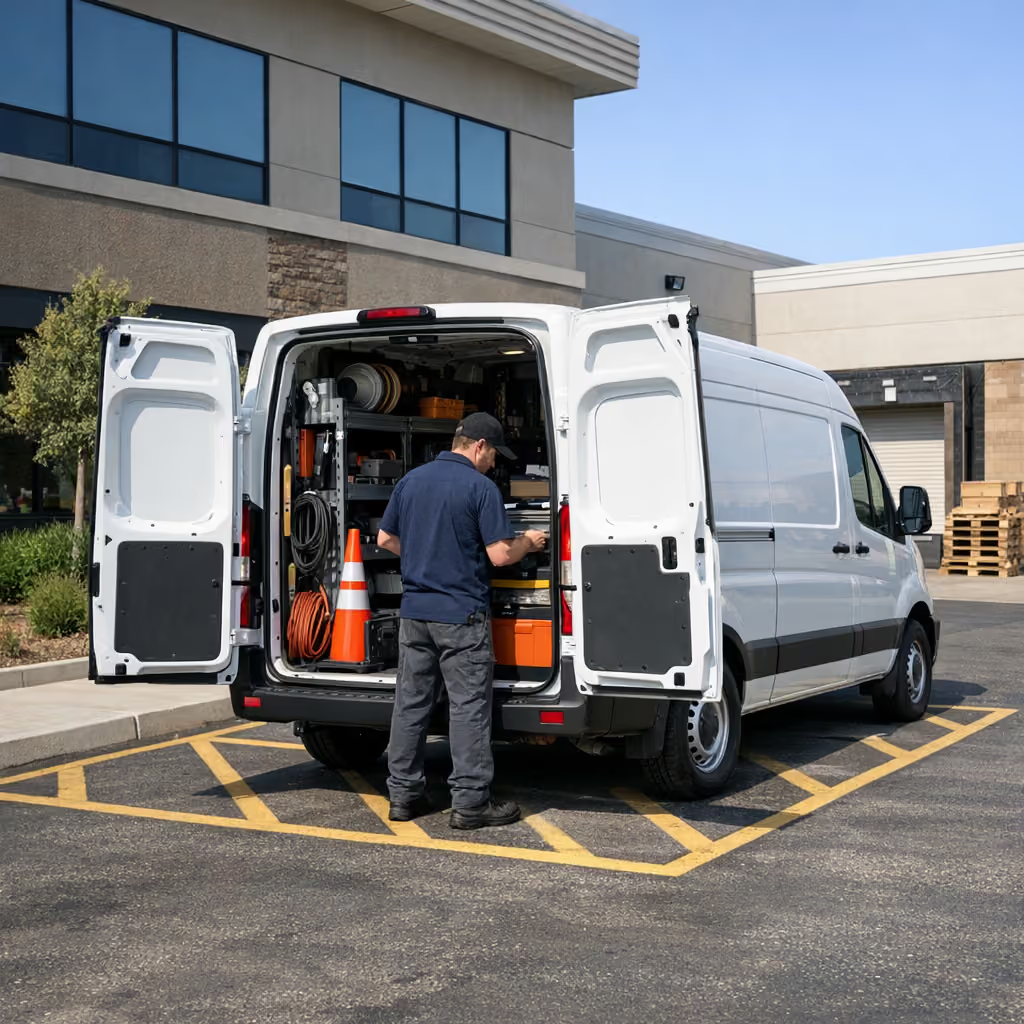
START WITH THE OPERATION
Four questions before comparing commercial auto options.
A vehicle used for work does not automatically fit a personal auto policy. The right discussion depends on ownership, drivers, business use and the terms of any available policy.
Who owns or leases each vehicle?
List the named business entity and the cars, vans, pickups or trucks it owns or leases. Ask which vehicles need to be scheduled and how additions or replacements should be reported.
Who drives and where?
Identify regular drivers, employees and anyone else who uses the vehicle. Where vehicles are garaged and how far they travel matter to the review; update the team as operations change.
Are rented or employee-owned vehicles used for work?
If you rent vehicles or employees use their own cars for business errands, ask about available hired and non-owned auto liability options. Do not assume a business policy covers physical damage to those vehicles.
What does the business carry or do?
Tell your agent about deliveries, tools, passengers, trailers or specialized equipment. Auto liability and physical-damage coverage do not necessarily protect cargo or loose tools; separate coverage may be needed.
POLICY DETAILS
Compare the terms, not only the vehicle list.
Review liability limits, collision and comprehensive options, deductibles and any uninsured/underinsured motorist, rental or roadside provisions available in the state. If a customer contract sets insurance requirements, check the actual policy and endorsements rather than assuming a certificate changes coverage.
Commercial auto is distinct from general liability and workers’ compensation. A licensed professional can help you look at the policies together.
Have these details handy
- Business name and state of operation
- Vehicle types, ownership and garaging locations
- Driver roles and typical travel or delivery use
- Any rented vehicles, trailers or employee-owned cars used for work
- Current limits, deductibles and contract requirements, if available
PERSONAL OR COMMERCIAL?
Tell us how the vehicle is actually used.
Using a personal car for business, a company van for deliveries or a pickup at jobsites can create different coverage questions. Do not assume a personal policy covers every business use—or that commercial auto automatically covers every driver, trailer or item inside the vehicle.
We begin with available Farmers options; where appropriate and permitted, our licensed team may explore approved additional markets. A licensed professional confirms carrier availability, vehicle and driver eligibility, policy language and price. A request does not bind or change coverage.
When to revisit the policy
A new vehicle, additional driver, changed delivery area or different work is a reason to call before assuming your current policy still fits. Ask how to report changes and when any revised coverage would take effect.
Colorado
Ask about hail, winter driving, deductibles and the work vehicles your team uses. Colorado guide.
Nebraska
Longer routes and changing weather make driver, roadside and vehicle-damage questions worth raising. Call (308) 216-3626 or see the Nebraska guide.
Arizona
Discuss commercial deliveries, garaging, glass and weather-related losses where relevant. Arizona guide.
COMMON QUESTIONS
Before requesting a review.
You can start with a conversation; the team will confirm what vehicle and driver details are needed for a quote.
Does my personal auto policy cover work use?
It depends on the use and policy language. Tell the team what kind of work the vehicle does before relying on personal coverage.
What if an employee drives their own car on a business errand?
Ask about non-owned auto liability and how the employee’s own policy interacts with it. Coverage for damage to that car is a separate question.
Are tools and goods in the van included?
Not automatically. Ask whether property in transit, tools and equipment need a separate policy or endorsement.
Is the form an instant quote?
No. It begins a consultation. A licensed team member confirms available products, necessary information and next steps; submitting does not change coverage.
READY TO TALK?
Request a commercial auto review.
Choose Business insurance on the form and include the state where your vehicles are garaged. Our team will follow up to learn about the vehicles, drivers and work involved. This is not an instant quote or a way to bind coverage.
Call Colorado at (303) 799-0909, Arizona at (480) 296-7414, or Nebraska at (308) 216-3626. Do not put sensitive details or policy documents in this brief form; share existing policy information securely when appropriate.
Maxwel Myers · Sales Team Lead
Consumer resource: The NAIC small-business insurance guide covers commercial auto, vehicle ownership and business-use considerations. Your actual policy and state-specific terms control.