RV and Car Insurance Bundles: When Combining Policies Makes Sense
The RV lifestyle is no longer strictly the domain of retirees. Today, the open road is calling to a broader, more diverse demographic. Over 11.2 million U.S. households now own a recreational vehicle, and the median age of an RV owner has dropped to just 49 years old.
Auto Insurance
By Matt Morand & Team · Published
6/22/2026
The Rising Popularity and Cost of the Open Road
The RV lifestyle is no longer strictly the domain of retirees. Today, the open road is calling to a broader, more diverse demographic. According to 2025 consumer data, over 11.2 million U.S. households now own a recreational vehicle, and the median age of an RV owner has dropped to just 49 years old. Families, remote workers, and weekend adventurers are embracing the freedom of traveling on their own terms, spending an average of 30 days a year in their rigs.
But as the popularity of RVing has surged, so have the costs associated with protecting these unique assets. Modern RVs are essentially rolling smart homes equipped with solar arrays, complex plumbing, and high end appliances. Due to rising repair costs and an increase in severe weather events, insurance premiums for RVs have climbed noticeably, with full time travelers seeing rate increases of over 20 percent in recent years.
As an RV owner, you are likely looking for ways to protect your investment without overpaying. At 5280 Insurance Agency, our mission is to act as your Personal CFO. We want to help you make informed, strategic decisions about your risk management. One of the most common questions we receive from clients who own a motorhome or travel trailer is whether they should combine their coverages. Let us explore when an RV and car insurance bundle makes sense, how it impacts your road trip liability, and the best ways to structure your policies for seasonal storage and maximum savings.
Why RV Insurance Is Fundamentally Different
Many first time buyers make the mistake of assuming their standard Auto Insurance policy will easily extend to their new RV. While auto insurance protects your liability on the road, an RV introduces an entirely different set of risks that a standard car policy simply is not built to handle.
Think of an RV as a hybrid between a vehicle and a house. If your daily commuter car breaks down, you might need a tow to the mechanic and a ride home. If your motorhome breaks down halfway across the country, you lose your transportation, your luggage storage, and your place to sleep all at once.
Proper RV insurance addresses these unique exposures through specialized coverages.
- Vacation Liability: When your RV is parked at a campground, it functions as a temporary residence. If a guest trips on your awning tie down and breaks their wrist, your auto liability will not cover their medical bills. Vacation liability acts like a homeowners premises liability policy while you are parked.
- Personal Effects Coverage: You likely pack your RV with camping gear, laptops, expensive bicycles, and specialized cooking equipment. A standard auto policy offers almost zero coverage for personal belongings, but an RV policy can provide comprehensive protection for the contents inside your rig.
- Emergency Expense Coverage: If your rig is disabled due to a covered loss far from home, emergency expense coverage helps pay for temporary lodging and transportation back home. Because the risks are so specialized, insuring an RV requires careful coordination with the rest of your insurance portfolio. This is exactly why looking into The Ultimate Guide to Insurance Bundling is highly recommended for anyone bringing a new recreational vehicle into their life.
Classes of RVs and How They Affect Your Bundle
Before you can determine the best strategy for your coverage, it helps to understand how the insurance industry categorizes RVs. The type of rig you own heavily dictates how it interacts with your existing auto policy.
- Motorhomes (Class A, B, and C): These are drivable units with their own engines. Because they are driven independently, they require their own bodily injury and property damage liability coverage. Putting a motorhome on an RV and car insurance bundle is highly advantageous because it ensures your liability limits are unified across all your drivable vehicles.
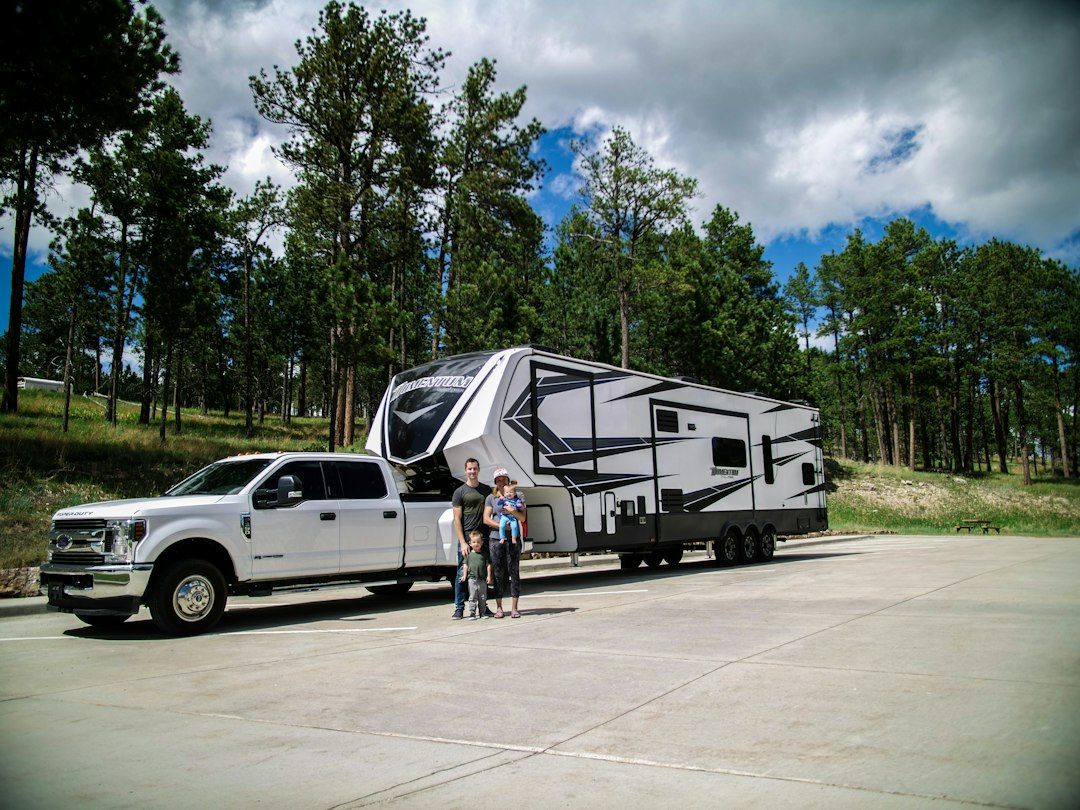
- Towables (Travel Trailers, Fifth Wheels, and Pop Ups): These units do not have an engine and must be pulled by a separate vehicle. In most states, a towable trailer automatically pulls its liability coverage from the towing vehicle while in motion. However, it still needs its own separate physical damage coverage (comprehensive and collision) and premises liability for when it is unhitched at the campground. If you own a travel trailer, bundling your coverage with the truck or SUV that tows it is arguably the most important move you can make. If an accident occurs while you are towing, having both the truck and the trailer insured by the same carrier eliminates the risk of two separate insurance companies arguing over who is responsible for the damages.
Key Advantages of an RV and Car Insurance Bundle
When you coordinate your coverage properly, combining your policies yields benefits that go far beyond a simple monthly discount. Here is why keeping your auto and RV policies under the same roof often makes sense.
Single Deductible Benefits If you encounter a severe hailstorm while driving your truck and towing your fifth wheel, both vehicles are going to sustain damage. If they are insured by two different companies, you will have to pay two separate deductibles. Many carriers offer a single loss deductible clause when you bundle. If an event damages both vehicles, you only pay one deductible, keeping more money in your pocket during a stressful time.
Streamlined Claims Processes Dealing with a major collision is chaotic enough. If you have an accident that damages your car, your trailer, and the personal belongings inside, navigating claims with two or three different carriers can turn into a logistical nightmare. A single carrier means one claims adjuster, one portal, and a much smoother path to getting back on the road.
Tiered Discounting Most homeowners are familiar with the standard discount for bundling home and auto, which is one of the easiest ways to lower premiums. However, insurance companies value clients who bring multiple lines of business to their portfolio. Adding a specialty vehicle to your existing home and auto package can bump you into a higher tier of savings, effectively reducing the cost of all three policies.
Managing Seasonal Vehicles: Storage and Off Season Savings
RVs are rarely driven year round. The average owner uses their rig for about a month out of the year, leaving the vehicle parked in a driveway or a storage facility for the remaining eleven months.
Much like the setup of an auto and boat insurance bundle, combining policies for seasonal vehicles allows you to better manage your coverages during the off season. When your RV goes into winter storage, it is no longer exposed to highway collision risks, but it is still vulnerable to theft, vandalism, rodent infestations, or a collapsed storage facility roof.
Through a carefully managed bundle, your Specialty Insurance provider can often help you suspend the collision and liability portions of your RV policy while keeping the comprehensive coverage active. This ensures your asset remains protected from stationary risks while saving you significant money on premiums during the months you are not driving it. Trying to manage seasonal coverage suspensions is much easier when you have a single independent agent overseeing your entire portfolio.
Insights from Your Personal CFO: A RamseyTrusted Approach
At 5280 Insurance Agency, we are proud to be a RamseyTrusted provider. We believe that insurance is not just a legal requirement; it is a critical defensive tool in your overall wealth building strategy. Our goal is to help you put people first, money second, and simplify the complex world of risk management.
When people start searching for the best bundle for home and car insurance, they often fall into the trap of prioritizing the cheapest monthly premium over actual protection. A cheap policy is completely useless if it leaves you exposed to bankruptcy in the event of a catastrophic accident.
Driving a massive Class A motorhome or towing a 10,000 pound fifth wheel introduces a significant amount of kinetic energy and, consequently, a massive amount of liability risk on the highway. If you cause a severe accident, the damages can easily exceed the standard liability limits of an auto policy. This is why we heavily emphasize the use of a Personal Umbrella Policy.
An umbrella policy sits on top of your underlying home, auto, and RV limits to provide an extra million dollars or more in liability protection. However, to qualify for an umbrella policy, your underlying coverage limits must meet specific minimums. When you split your home, auto, and RV across three different discount carriers, it becomes incredibly difficult to sync those underlying limits. Bundling your policies allows us to ensure that the foundation of your coverage is solid, allowing a unified umbrella policy to snap into place and protect your family's financial future seamlessly.
Furthermore, we always educate our clients on the difference between Actual Cash Value (ACV) and Total Loss Replacement. RVs depreciate rapidly. If you buy a brand new rig and total it three years later, an ACV policy will only pay you what the used rig was worth at the time of the crash, leaving you underwater on your loan. We can help you secure agreed value or replacement cost coverage so that a total loss does not derail your financial goals.
How to Shop and Compare Multi-Policy Options
If you are ready to evaluate your current setup, it pays to be methodical. During a multi-cover car and home insurance comparison, it is very easy to look strictly at the final dollar amount and miss the nuances in the policy declarations.
Here are three steps we recommend when reviewing your options:
- Evaluate the Carrier's Specialty Experience: Not all auto insurance companies handle RV claims well. You want to make sure the carrier you bundle with has a dedicated specialty claims department that understands how to source specialized RV parts and values the unique features of a motorhome.
- Look for Hidden Endorsements: Ensure the quotes include vacation liability, personal effects coverage, and specialized roadside assistance that covers towing an RV (which requires heavy duty wreckers).
- Use an Independent Broker: Instead of bouncing between generic comparison sites, work with an independent agency. We are not beholden to any one carrier. We can run your profile through dozens of highly rated companies to see which one offers the most robust package for your specific mix of properties and vehicles. For more advice on navigating the quoting process, check out our guide on How to Compare Home & Car Insurance Quotes Online and our tips on Shopping for Home and Auto Insurance: Balancing Ratings, Reviews, and Real-World Fit.
Conclusion
Owning an RV opens the door to incredible adventures and lifelong memories. But the peace of mind required to truly enjoy the open road only comes when you know your family, your assets, and your financial future are fully protected.
Whether you are navigating the complexities of cross policy deductibles, looking to suspend coverage during the winter storage months, or striving to build an impenetrable liability shield with an umbrella policy, bundling your RV and auto coverage is often the smartest strategic move you can make. By taking a Personal CFO approach to your insurance portfolio, you can eliminate coverage gaps, simplify your life, and ensure you are getting the absolute best value for your premium dollars.
5280 Insurance Agency
Ready to take the next step? Sign up now to access exclusive insights tailored for your needs, or contact us today for a personalized quote that empowers your success. Let’s start your journey together! At 5280 Insurance Agency, we are committed to acting as your Personal CFO, providing honest advice and customized risk management solutions that fit your values and your budget. Whether you need to insure your home, your vehicles, or your weekend toys, our independent team is ready to deliver clarity and confidence. Reach out today and let us simplify your insurance experience.
About the author
Matt Morand, CIC, CRM, LUTCF, and the 5280 team share practical guidance drawn from insurance, risk management, financial services, and client education experience.
Have a question about this topic?
Talk with the 5280 team about the context, tradeoffs, and next step that fit your situation.